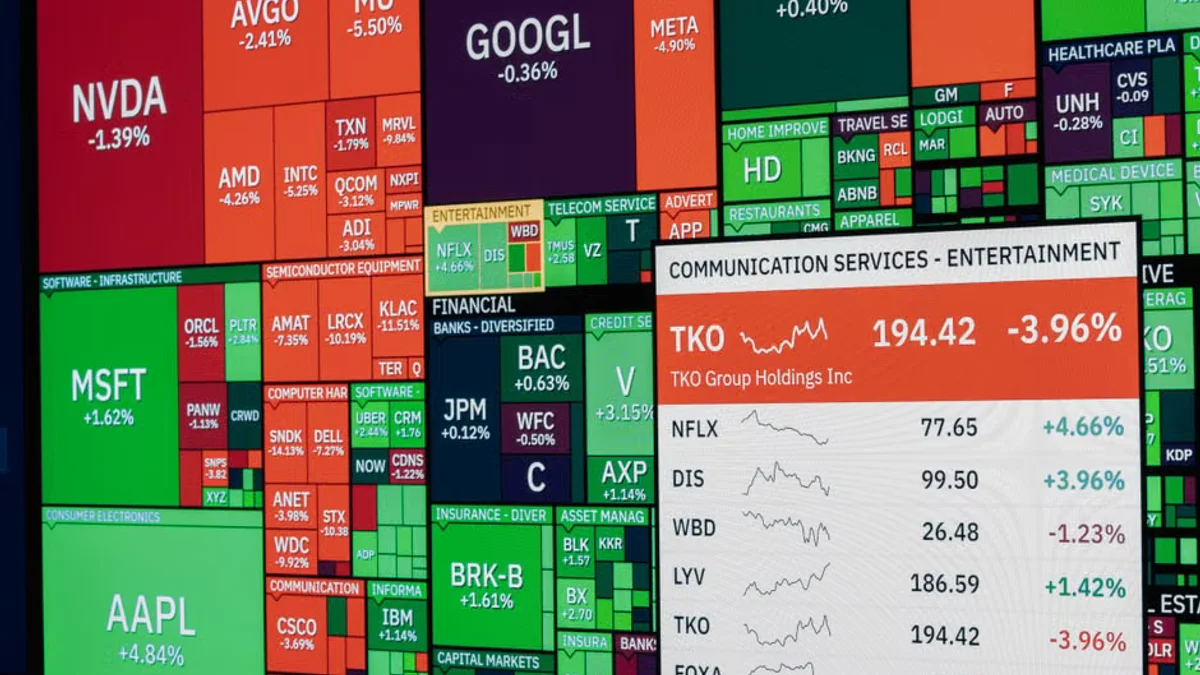
Wall Street trading desks have recalibrated their monetary policy forecasts following recent commentary from economic analysts indicating that the Federal Reserve is increasingly likely to maintain benchmark interest rates at its upcoming October meeting. Financial markets had previously priced in aggressive easing cycles, but resilient macroeconomic data has forced a reassessment of the central bank's timeline.
Inflation metrics, while showing general moderation from their post-pandemic peaks, continue to hover above the Fed's targeted two percent threshold. Concurrently, labor market resilience has given policy architects the latitude to adopt a patient, data-dependent stance rather than rushing into preemptive rate cuts. Bond yields fluctuated moderately following the reports, reflecting a divided sentiment among institutional investors.
Chief economists note that corporate earnings reports and upcoming employment employment figures will play a decisive role in shaping Federal Open Market Committee (FOMC) deliberations. While equities experienced mild volatility, overall market sentiment remains anchored to the central bank's overarching commitment to achieving a soft landing.
As global financial institutions navigate an increasingly complex macroeconomic landscape, clarity on interest rate trajectories remains the primary catalyst for equity and debt market performance.
Key Highlights
- Markets adjust expectations toward a Federal Reserve rate hold in October.
- Resilient labor data and sticky inflation influence central bank calculus.
- Bond yields experience moderate fluctuations following policy outlook shifts.
- Investors await upcoming employment and inflation prints for further direction.
The central bank's deliberate approach underscores the delicate balance required to tame inflation without triggering broader economic contraction.