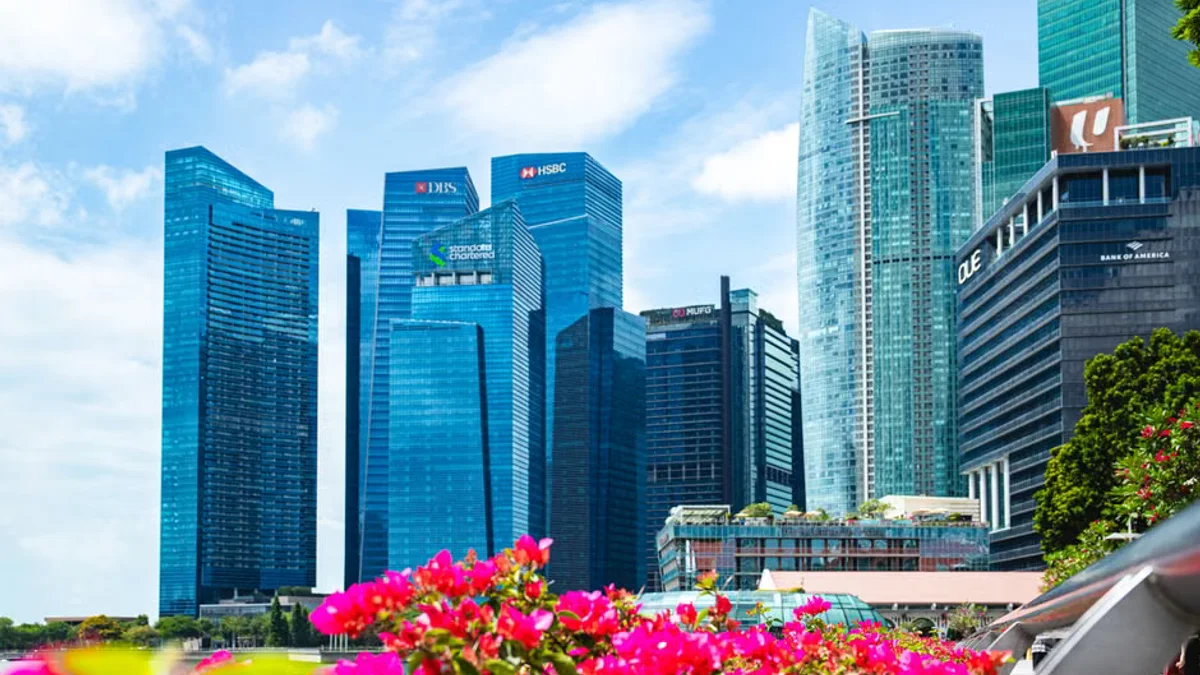
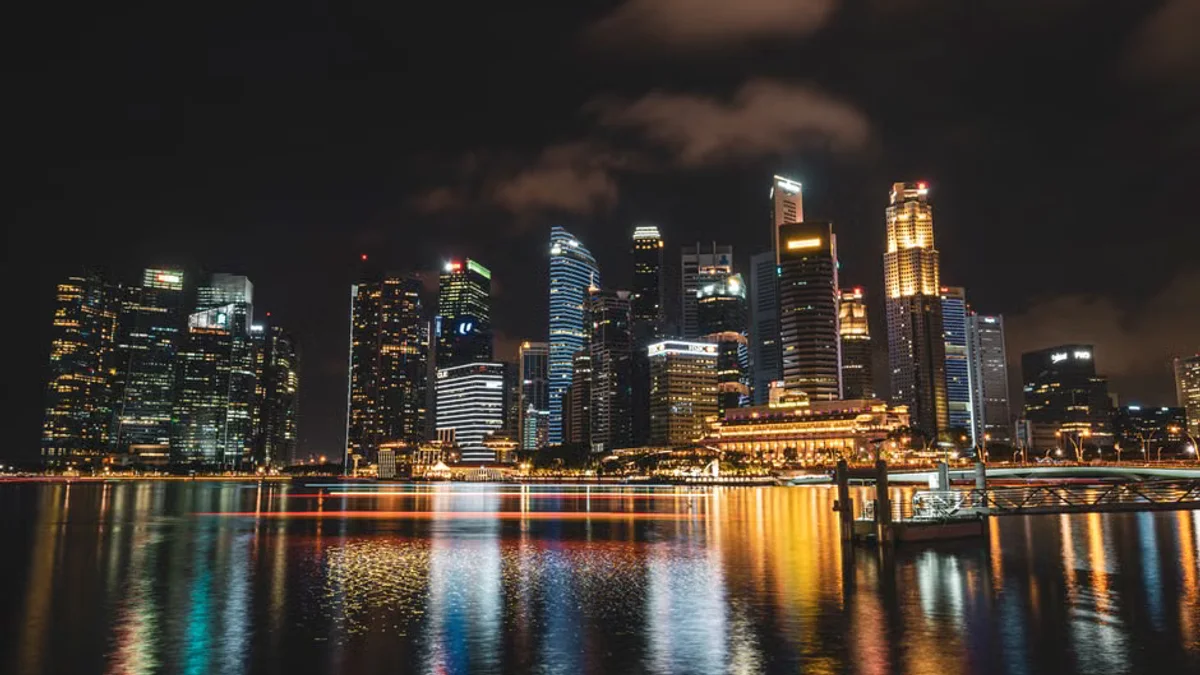
Singapore's banking sector faced a challenging trading session as major lenders saw their share prices dip amid growing concerns over regional economic headwinds and shifting monetary policies. Financial analysts note that the recent pullback reflects broader anxieties regarding slowing loan growth, compressed net interest margins (NIMs), and volatile global debt markets.
As a leading international financial hub, Singapore's domestic banks—traditionally seen as bellwethers for Southeast Asian economic health—are acutely sensitive to external trade dynamics and interest rate trajectories set by major global central banks. Market participants are re-evaluating risk premiums across emerging markets, leading to cautious capital allocation and short-term profit-taking in local equities.
Despite the immediate downward pressure, institutional investors remain confident in the robust capital buffers and stringent regulatory frameworks overseen by the Monetary Authority of Singapore (MAS). These strong fundamentals provide a significant cushion against systemic shocks, even as individual lenders adjust their strategic forecasts for the upcoming fiscal quarters.
The current market correction also underscores the growing intersection between traditional banking and broader technological integration, as institutions allocate heavily toward digital infrastructure and artificial intelligence risk management to secure long-term operational efficiencies. Stakeholders will be watching upcoming earnings guidance for clearer indicators on credit quality and wealth management fee income.
Key Highlights
- Major Singapore banking equities faced downward pressure amid macro shifts.
- Concerns focus on compressed net interest margins and moderating loan growth.
- MAS regulatory buffers continue to offer strong systemic resilience.
Ultimately, while short-term sentiment remains cautious, the structural advantages of Singapore's financial ecosystem position it well to navigate ongoing global economic transitions.