Global energy markets are experiencing heightened volatility this week as diesel supply constraints and fluctuating refining margins send ripples through North American and European logistics networks. As the lifeblood of heavy transport, agriculture, and manufacturing, diesel fuel pricing directly influences broader economic inflation, making these inventory shifts a critical indicator for central banks.
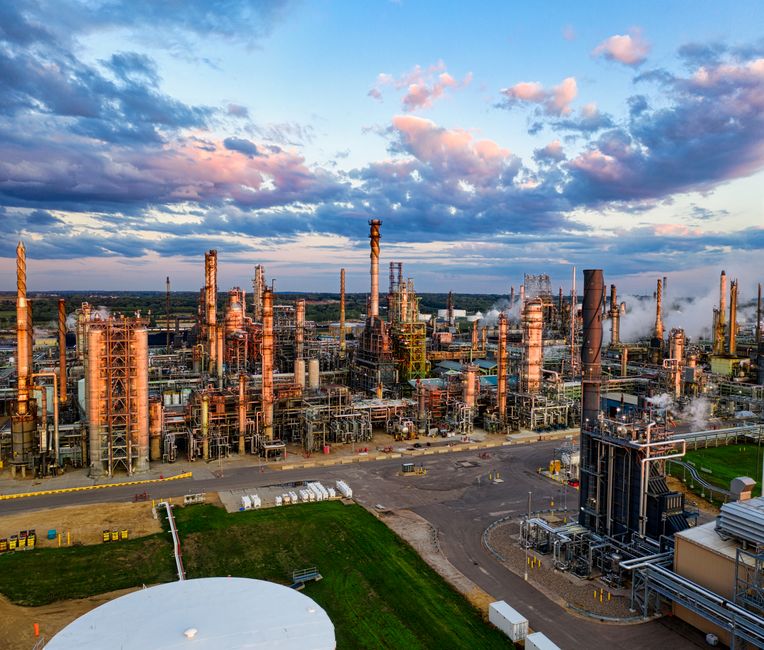
Industry analysts point to a combination of unexpected refinery outages, lower-than-average seasonal stockpiles, and shifting geopolitical trade flows as primary drivers behind the tightening market. With European importers competing for non-Russian distillate sources and North American inventories hovering below five-year seasonal averages, downstream fuel purchasers are bracing for sustained price volatility.
Transportation associations have warned that escalating fuel surcharges will inevitably squeeze profit margins for freight carriers and supply chain operators, threatening to pass higher costs onto retail consumers. Meanwhile, energy analysts are urging policymakers to review strategic petroleum reserves and long-term refining capacity investments to mitigate vulnerability to sudden international supply shocks.
Key Highlights
- Diesel inventories remain below five-year seasonal averages in key Western markets.
- Logistics and transport sectors face immediate profit margin compression from fuel surcharges.
- Geopolitical shifts and refinery maintenance schedules exacerbate global supply tightness.
As global demand patterns adapt to tightening energy constraints, market participants will closely watch upcoming weekly inventory reports from the U.S. Energy Information Administration and international energy agencies for definitive signs of stabilization.


